Check My Credit Score: How to Check It Free in the UK and What Your Score Means
“Check my credit score” is one of the most searched personal finance phrases in the UK, and for good reason. Your credit score influences whether you are accepted for credit cards, loans and mortgages, and sometimes even for a mobile contract or a rental home. Yet many people have never checked theirs, or have checked it once and been confused by what they found. This guide explains how to check your credit score free, what the number actually means, why it differs between agencies, and what genuinely improves it.
Disclaimer: this article is general information only and is not personal financial advice. If you are struggling with debt, free help is available from organisations such as StepChange, National Debtline and Citizens Advice.
What Is a Credit Score?
A credit score is a number that summarises, in simplified form, the information on your credit file. Credit reference agencies in the UK, Experian, Equifax and TransUnion, each produce their own score based on the data they hold about you: your accounts, your repayment history, your addresses, and public records such as County Court Judgments. Lenders use the underlying file, plus their own criteria, to decide whether to lend and on what terms.
The most important thing to understand is that there is no single, universal credit score in the UK. Each agency scores on a different scale, holds slightly different data, and weighs factors differently. A lender may check one agency, another, or several, and may apply its own scoring on top. Your score is therefore best treated as a guide to the health of your file, not as a pass mark that guarantees acceptance or rejection.
How to Check Your Credit Score Free
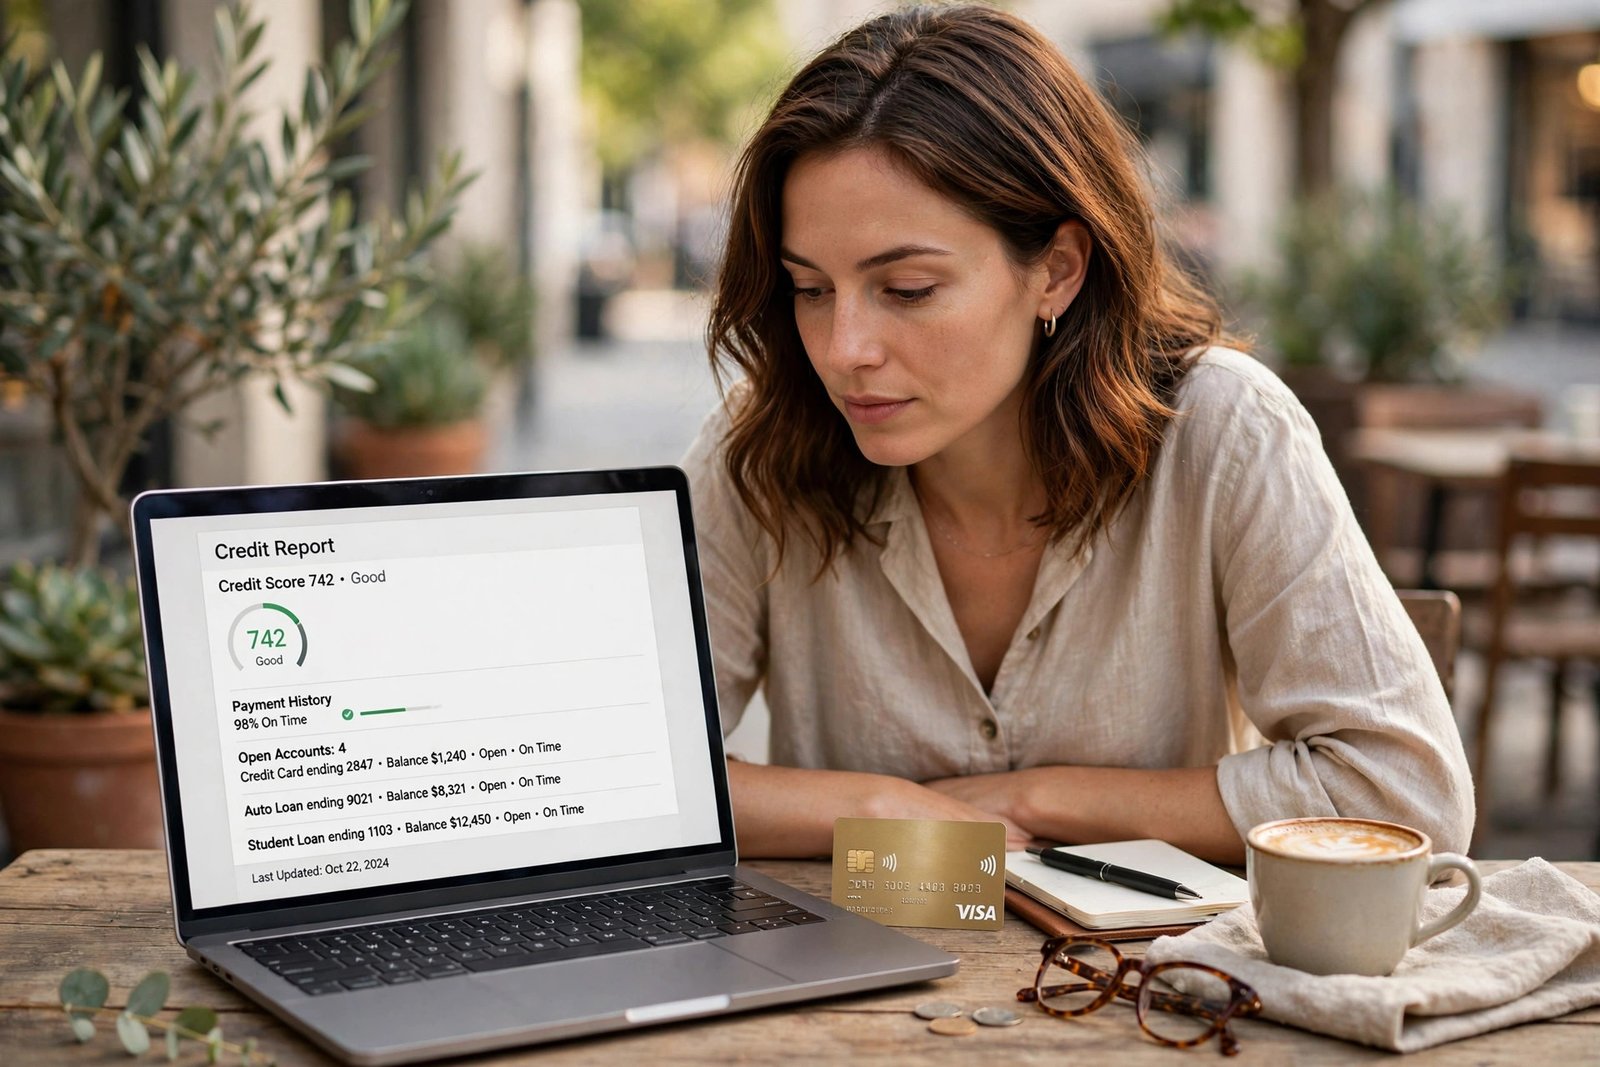
You can check your credit score free through each of the three main agencies, either directly or through their free partner services. These free services show your score and usually a summary of your file, including your accounts, your repayment history and any recent searches. Checking your own score is a soft check: it is visible only to you and has no effect on your score or on lending decisions, so you can check as often as you like.
Because lenders may check any of the three agencies, it is worth reviewing all three files at least once. An account reported to one agency may be missing from another, and an error on one file will not automatically be corrected on the others. Set a routine, such as checking one agency every few months on rotation, so your files stay monitored without becoming a chore.
There is no need to pay for a premium credit monitoring service to see your score. Free services provide the file and the score, and paid extras, such as identity monitoring alerts, rarely change lending outcomes. Spend your effort on the file itself, not on a subscription dashboard, and be cautious of any service that promises to boost your score for a fee.
Why Scores Differ Between Agencies
Seeing three different numbers for the same person surprises many people, but it is normal. Each agency collects data from lenders independently, and not every lender reports to all three agencies. If a loan is reported to one agency but not another, the two files differ, and the scores built on them differ too. Public records and electoral roll data can also be recorded slightly differently across agencies.
The scoring scales differ as well. One agency may score out of a lower maximum than another, so the same file health produces a different-looking number in each place. What matters is not the raw number but the band it falls into, such as fair, good or excellent, and more importantly, the underlying file: are the details accurate, are payments on time, and is usage sensible? A high number built on an inaccurate file is less valuable than a slightly lower number built on a clean, accurate one.
Lenders add their own layer on top. A lender’s decision uses the file data plus its own affordability assessment, including income and outgoings, and its own appetite for risk in a given product. That is why you can be accepted by one lender and declined by another on the same week, even though your score has not changed. Focus on the file, not on chasing a single number.
What Your Score Does and Does Not Show
Your credit file shows your borrowing and repayment history, your addresses, your electoral roll registration, and public records. It does not show your salary, your savings balance, or your day-to-day spending, although lenders will usually ask about income and outgoings separately. It also does not show every financial fact about you: some buy-now-pay-later arrangements and rental payments are reported inconsistently, so a responsible payment history in those areas may not yet appear on every file.
A score also does not capture context. It cannot tell a lender that a missed payment coincided with an illness, a job loss or a bank error, although you can add a short notice of correction to your file explaining a disputed entry in your own words. This is why checking the file itself, not just the score, matters: errors and outdated information can be disputed and corrected, and a correction can matter more than any number.
For a fuller picture of what lenders see when they look at your file, our guide to credit checks explains the check process step by step, including the difference between soft and hard checks and what each type of search means for your score.
What Genuinely Improves a Credit Score
Improving a score takes time, but the steps are straightforward and well established. Register on the electoral roll at your current address, since lenders use it to confirm identity and address history, and an unregistered address is one of the easiest problems to fix. Pay every bill on time, and set up Direct Debits for at least the minimum payment, so a forgotten date never becomes a missed payment.
Keep your credit usage low relative to your limits. Consistently borrowing close to a limit can look risky even if you never miss a payment, so spreading spending across cards, or paying down balances before a statement date, can help. Avoid applying for several products in quick succession, since a cluster of hard checks can temporarily lower your score and make the next decision harder.
If you have little or no credit history, a small, well-managed product designed for building credit can help, provided you use it lightly and clear the balance in full each month. Our guide to the Zempler credit card explains how one such credit builder card works, including its eligibility checker, which lets you gauge your chances with a soft check before a full application. Keep older, well-managed accounts open where sensible, since a longer visible history usually supports a stronger file.
Common Myths About Credit Scores
- Checking your own score lowers it: False. Your own checks are soft checks, visible only to you, with no effect on lending decisions.
- There is one national score: False. Each agency scores differently, and lenders apply their own criteria on top.
- A high income guarantees a high score: False. Your file does not show income; it shows borrowing and repayment behaviour.
- Closing old cards always helps: Not usually. Closing your oldest card can shorten your visible history.
- Paying a service can erase accurate negative information: False. Genuine errors can be disputed free; accurate adverse information stays until it expires, usually after six years.
- A perfect score guarantees acceptance: False. Lenders also assess affordability and their own risk appetite for each product.
What to Do If Your Score Is Lower Than Expected
First, look at the file, not just the number. Check for errors: wrong addresses, accounts that are not yours, balances that are out of date, or missed payments you do not recognise. Report anything wrong to the agency and to the lender concerned, and keep copies of your correspondence. A single corrected error can change the picture significantly.
Next, look for the likely cause. A recent missed payment, high usage, a thin file, or several recent applications each point to a different remedy, and fixing the wrong one wastes time. If borrowing is not essential, waiting and rebuilding is often the strongest move, since negative information fades with time and positive habits accumulate. If you need credit soon, use soft-check eligibility tools to shortlist products you are likely to be accepted for, rather than triggering hard checks on speculative applications.
Be wary of quick fixes. No legitimate service can remove accurate information early, and suggestions to invent information or open accounts under false details are fraud, with serious consequences. The honest route, accurate files, on-time payments, low usage and patience, is slower, but it is the only route that actually works.
Frequently Asked Questions
How often should I check my credit score?
Checking every few months is sensible, rotating between agencies so each file is reviewed regularly. Check more often if you are about to apply for a mortgage or a large loan, or if you suspect identity fraud.
Does checking my own credit score affect it?
No. Your own checks are soft checks, visible only to you, and they never lower your score or affect a lender’s decision.
Why is my score different on different sites?
Each agency holds slightly different data and uses its own scoring scale, and lenders apply their own criteria too. Compare the bands and the underlying files, not the raw numbers.
How long does it take to improve a credit score?
Small improvements, such as registering on the electoral roll, can help quickly. Rebuilding after missed payments takes longer, since most negative information remains visible for six years, though its impact fades as newer positive history builds.
Conclusion
Checking your credit score is free, harmless and genuinely useful, but the number is only the beginning. Look at the file behind it, check all three agencies, fix errors promptly, and focus on the habits that build a strong file over time: accurate details, on-time payments, low usage and patience. Do those things consistently, and your score will reflect them, not overnight, but steadily, and the next time a lender looks at your file, it will be seeing the strongest version of your financial history.

Post Comment