Credit Check: What It Is, How It Works in the UK, and How to Prepare
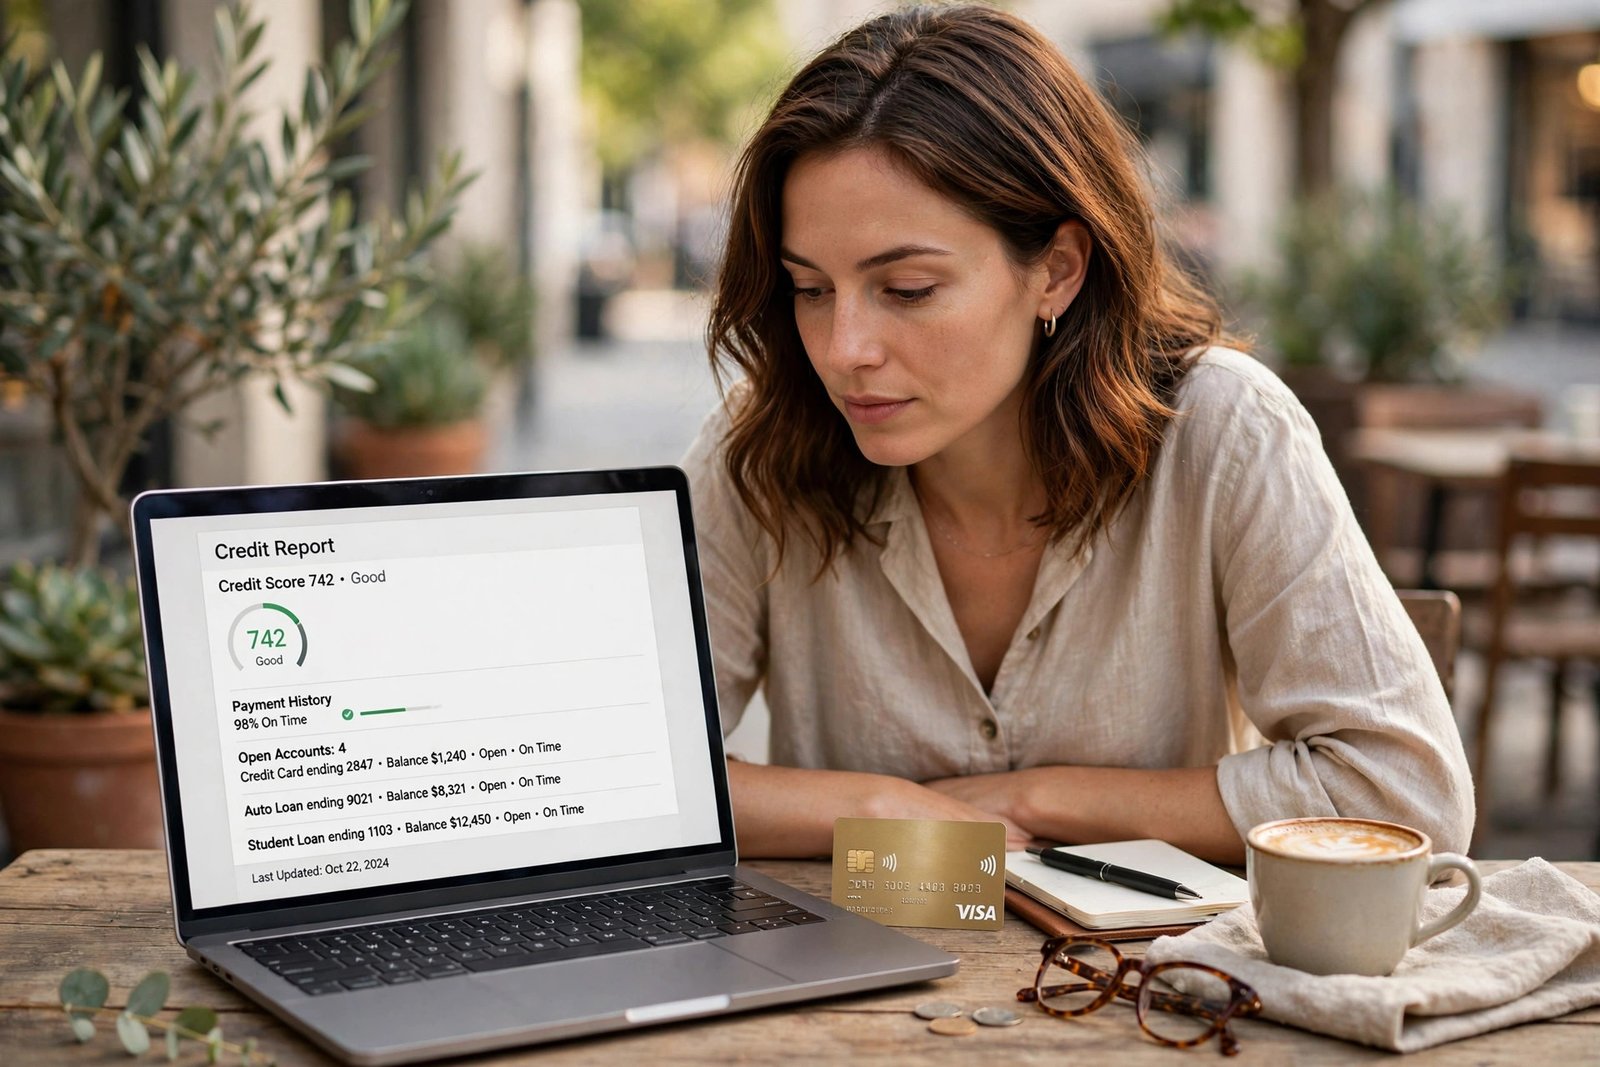
A credit check is one of the first things that happens when you apply for credit in the UK, whether that is a credit card, a loan, a mobile phone contract, or a mortgage. It can feel mysterious, especially when an application is declined and nobody explains exactly why. In reality, a credit check is simply a lender looking at your credit file to judge how likely you are to repay what you borrow.
Understanding how credit checks work puts you in a much stronger position. You can see the same information lenders see, fix mistakes before they cost you an approval, and avoid the common errors that drag a file down. This guide explains what a credit check is, what it shows, the difference between soft and hard checks, and how to prepare your file before you apply.
Disclaimer: this article is general information only and is not personal financial advice. If you are struggling with debt, free help is available from organisations such as StepChange, National Debtline and Citizens Advice.
What Is a Credit Check?
A credit check is a review of your credit file, which is a record of your borrowing and repayment history held by a credit reference agency. In the UK, the three main agencies are Experian, Equifax and TransUnion. Lenders, and sometimes landlords and employers, ask one or more of these agencies for your file when they need to assess risk.
Your file does not contain a single universal score that every lender uses. Each agency produces its own score, and each lender applies its own criteria on top of the file data. That is why you can be accepted by one lender and declined by another, and why your score can differ between agencies. The file itself matters far more than any one number attached to it.
What Does a Credit Check Show?
A typical UK credit file contains your name, date of birth, current and previous addresses, and whether you are on the electoral roll at your address. It lists your credit accounts, such as credit cards, loans, overdrafts, mortgages and some buy-now-pay-later arrangements, along with their balances, credit limits and repayment history.
It also records public information such as County Court Judgments, bankruptcies and Individual Voluntary Arrangements, and it shows recent searches made on your file by other organisations. What it does not show is your salary, your savings balance, or your day-to-day spending, although lenders will usually ask about income and outgoings separately as part of an affordability assessment.
One detail surprises many people: a credit file is built over time. If you have never borrowed, or never had an account in your name, your file may be thin, and lenders may have little to judge you on. That is not the same as having a bad file, but it can still make approval harder, because the lender cannot see evidence of reliable repayment.
Soft Checks vs Hard Checks
Not all credit checks are equal, and the distinction matters. A soft check, sometimes called a soft search or quotation search, is visible only to you. It does not affect your score, and other lenders cannot see it. Eligibility checkers, price-comparison tools and your own credit report checks all use soft checks, which is why they are safe to use as often as you like.
A hard check, or hard search, is recorded on your file and is visible to other lenders. It happens when you make a full application for credit. A single hard check has only a small, short-lived effect for most people. The problem comes from several hard checks in a short period, which can look like financial distress or a rush to borrow, and may lower your score temporarily.
The practical rule is simple: use soft-check eligibility tools to shortlist products you are likely to be accepted for, and only trigger a hard check when you actually intend to apply. Spreading applications out, rather than applying for several products in one week, protects your file from unnecessary damage.
Who Carries Out Credit Checks?
Lenders are the most common users, but they are not the only ones. Landlords and letting agents may check a prospective tenant’s file before agreeing a tenancy. Some employers run checks for roles involving financial responsibility. Mobile networks, insurers offering monthly payments, and utility providers may also check your file before opening an account.
Each of these users looks for something slightly different. A mortgage lender studies the whole picture in depth, including historic missed payments and total outstanding balances. A mobile provider may only need a basic check that you have no serious adverse history. Knowing who is checking helps you understand what matters: for a mortgage, years of clean history count; for a phone contract, a recent serious default is the main risk.
How to Check Your Own Credit File
You can view your credit file for free through each of the three main agencies, either directly or through free partner services. Because lenders may check any of the three, it is worth reviewing all of them at least once, as the information they hold can differ. An account reported to one agency may be missing from another, and an error on one file will not automatically be fixed on the others.
When you review your file, check four things carefully. First, are your name and addresses correct, and are you registered on the electoral roll at your current address? Second, are all the accounts listed actually yours, with correct balances and statuses? Third, are there any missed or late payments you do not recognise? Fourth, are there any hard searches you did not authorise, which could indicate identity fraud? Report anything wrong to the agency and to the lender concerned, and keep copies of your correspondence.
How a Credit Check Affects Your Score
Several factors shape how a lender reads your file. Payment history carries the most weight: regular on-time payments build trust, while missed or late payments damage it, and serious events such as defaults stay visible for years. How much of your available credit you use also matters; consistently borrowing close to your limit can look risky even if you never miss a payment.
The length of your credit history, the mix of account types, and the number of recent applications all play a part too. Closing your oldest card can shorten your visible history, which is one reason it is usually better to keep an old, well-managed account open rather than closing it. Opening many new accounts at once, by contrast, can make a file look unstable.
How to Improve Your Credit File
Improving a credit file is a slow process, but the steps are straightforward. Register on the electoral roll at your current address, since lenders use it to confirm your identity and address history. Pay every bill on time, and set up Direct Debits for at least the minimum payment so a forgotten date never becomes a missed payment.
Keep your credit usage low relative to your limits, and avoid maxing out cards even for short periods. Avoid applying for several products in quick succession, and give your file time to recover after a hard check. If you have no credit history at all, a small, well-managed product designed for building credit can help, provided you use it lightly and clear the balance in full each month. Our guide to the Zempler credit card explains how one such credit builder card works, including its eligibility checker, which lets you gauge your chances with a soft check before a full application.
What to Do If You Are Declined
A declined application is frustrating, but it is not the end of the story, and it is not a verdict on you as a person. Ask the lender which agency it checked, then review that file for errors or outdated information. You have the right to ask the lender to reconsider if you can show that the information it relied on was wrong, and you can add a short notice of correction to your file explaining a disputed entry in your own words.
Resist the urge to apply again immediately elsewhere, since a cluster of hard checks can make the next decision harder. Instead, take time to understand the likely reason: it may be a thin file, a recent missed payment, high usage, or simply that the product was aimed at a different risk profile. If borrowing is not essential, waiting and rebuilding is often the strongest move. If you need an alternative urgently, research carefully and compare options before applying, as our guide to what happened to SafetyNet Credit and the alternatives available in the UK illustrates for one short-term lender that is no longer trading.
Be wary of any company that promises to repair your credit file for a fee, or that suggests inventing information. You can dispute genuine errors yourself for free, and no legitimate service can remove accurate adverse information before it is due to expire.
Credit Checks and Identity Fraud
Credit files are also an early warning system for identity fraud. If someone applies for credit in your name, the hard search and the new account will appear on your file. Checking your file regularly, and acting quickly on anything unfamiliar, limits the damage. If you suspect fraud, contact the lender and the agency, ask for a fraud marker if appropriate, and consider reporting it to Action Fraud. A protective registration with the fraud prevention service CIFAS is another option if your identity documents have been lost or stolen.
Frequently Asked Questions
Does checking my own credit file lower my score?
No. Checking your own file is a soft check. It is visible only to you and has no effect on your score or on lending decisions.
How long do missed payments stay on a credit file?
Most negative information, including missed payments and defaults, remains visible for six years from the date of the event in the UK. After that it drops off, although lenders may still ask about past difficulties directly.
Can I get credit with no credit history?
Yes, but your options are narrower. Products designed for people building credit, a mobile contract in your name, or being added as an authorised user where appropriate can all start building a record. Paying rent on time can also help if your landlord or a rent-reporting service shares that data.
Why do different agencies show different scores?
Each agency holds slightly different data and uses its own scoring model. Lenders also apply their own criteria, so the score is a guide, not a pass mark. Focus on the underlying file: accurate details, on-time payments and low usage.
Should I pay to see my credit score?
There is no need to pay. Free services give you access to your file and score from each agency, and the paid extras rarely change lending outcomes. Spend the effort on the file itself, not on a premium dashboard.
Conclusion
A credit check is not a mystery test with a single pass mark. It is a lender reading your financial history and deciding whether the evidence supports lending to you. Check your own files regularly, fix errors promptly, use soft-check eligibility tools before applying, and give your file time to reflect good habits. Do those things consistently, and the next credit check you face will be working with the strongest version of your history, not against it.

Post Comment