Mortgage Payment Calculator Explained: How It Works, What It Shows, and What It Does Not Show
What Is a Mortgage Payment Calculator?
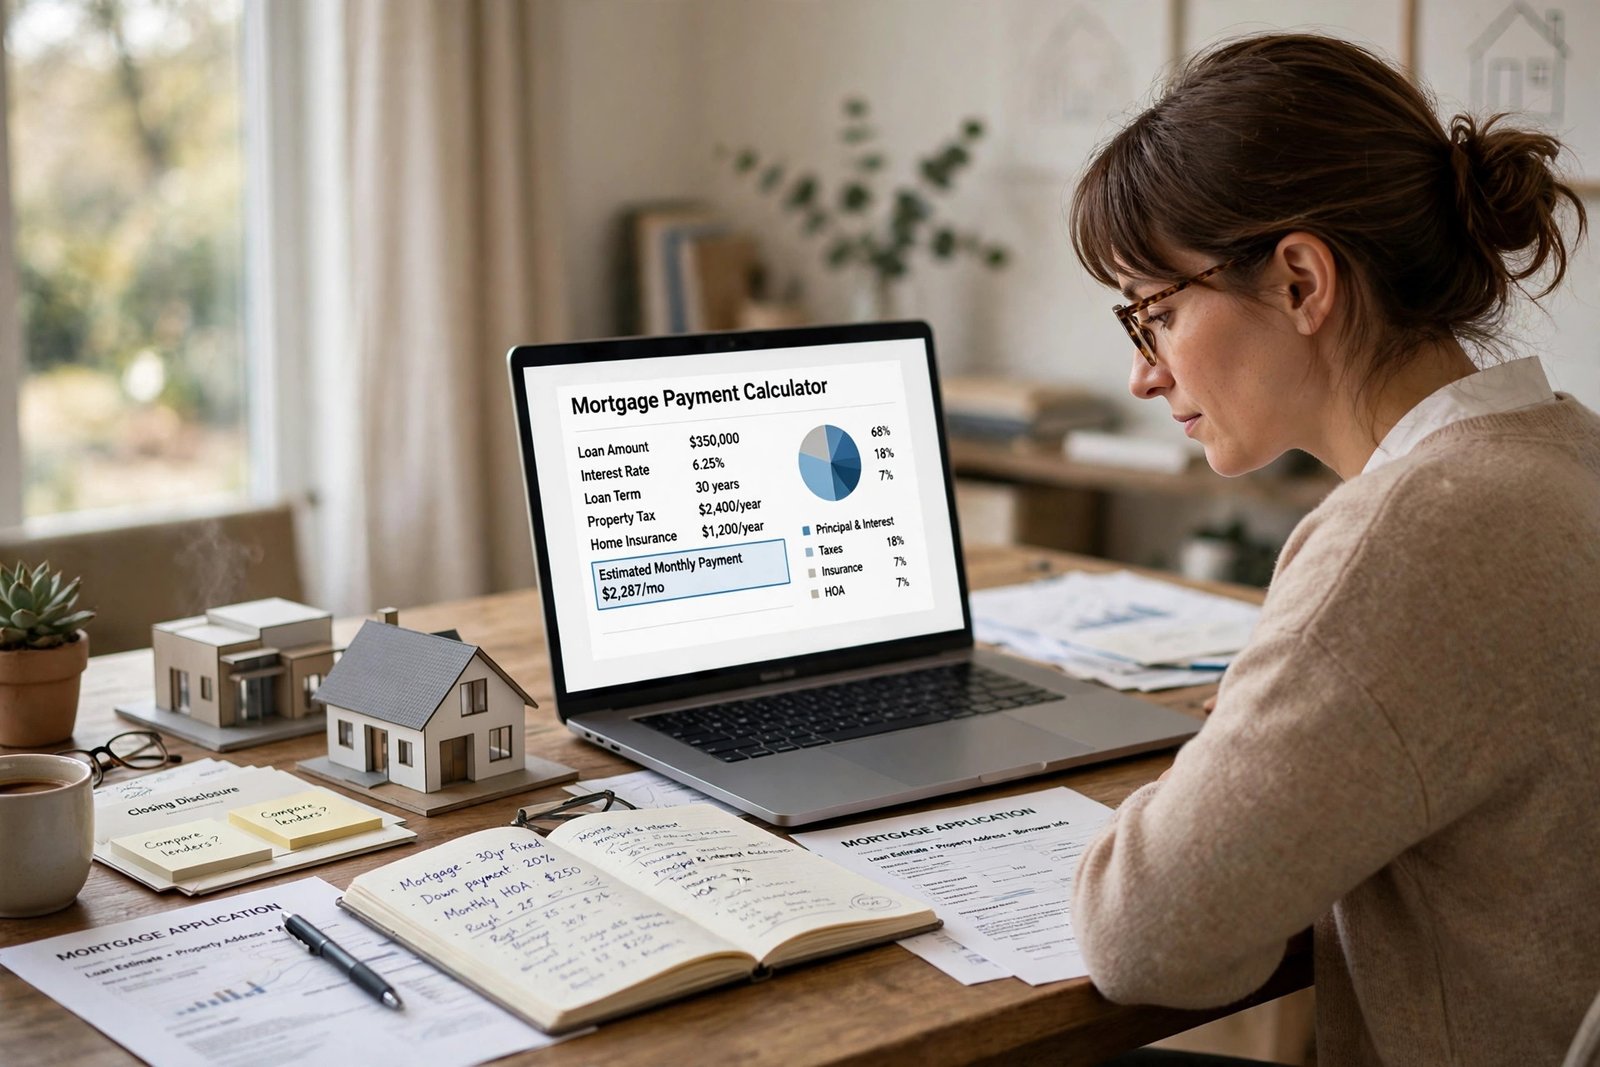
A mortgage payment calculator is a tool that turns a small set of figures about a possible mortgage into an estimated monthly payment. It does not make a decision for you, and it does not approve anything. Instead, it gives you a way to explore how the main parts of a mortgage fit together, so that you can understand the shape of a repayment plan before you look at any other detail. When used carefully, it can help you see why two mortgages that look similar at first glance can lead to very different monthly payments and very different totals over time.
The value of such a calculator lies in its simplicity. You enter a few inputs, and it applies a standard calculation to produce an illustration. That illustration is useful precisely because it is consistent: if you change only one input, you can see what changes as a result. At the same time, that simplicity is also its limit. A calculator can only work with the information you give it, and it cannot know about your wider circumstances, your future plans, or the many costs and conditions that sit outside the basic calculation.
The Inputs a Calculator Needs
Every mortgage payment calculator asks for the same core information, even if the exact layout differs from one tool to another. The loan amount is the amount that would be borrowed after any deposit is taken into account. The deposit is the amount put towards the purchase from your own resources, which reduces the amount that needs to be borrowed. The term is the length of time over which the loan would be repaid. The interest rate is the cost of borrowing, expressed as a rate applied to the outstanding balance. Finally, the calculator needs to know whether the plan is repayment or interest-only, because that choice changes what each monthly payment is actually doing.
- Loan amount: the sum borrowed after the deposit.
- Deposit: the contribution that reduces the amount borrowed.
- Term: the period over which repayments are spread.
- Interest rate and rate type: the cost of borrowing and how that rate may behave.
- Repayment or interest-only: whether payments reduce the balance, cover interest alone, or follow another agreed structure.
The term deserves particular attention, because it has a strong effect on the monthly figure. Spreading repayments over a longer term generally lowers the estimated monthly payment, since the same borrowed amount is divided across more payments. That lower monthly figure does not mean the overall cost is lower. In general, a longer term means interest is charged for longer, so the total interest illustration tends to be higher. A shorter term usually produces a higher monthly payment, but the loan is cleared sooner and the total interest illustration tends to be lower. A calculator lets you compare those trade-offs side by side, without needing to work through the arithmetic yourself.
The interest rate and its type also matter a great deal. Some rates stay fixed for an agreed period, while others can move up or down in line with wider conditions or a lender’s own terms. A calculator normally applies a single rate across the whole illustration, even if the real arrangement might change later. That is why it is important to treat the result as a snapshot based on the rate you entered, rather than as a promise about what will happen in future years. Likewise, the difference between repayment and interest-only is fundamental. With a repayment plan, each monthly payment is designed to cover interest and reduce the balance, so that the loan is cleared by the end of the term if payments are made as planned. With an interest-only plan, monthly payments cover interest, while the original borrowed amount remains to be dealt with separately at the end of the term, through an agreed plan that sits outside the calculator.
What the Outputs Show
The most prominent output is the estimated monthly payment. This is the regular amount the calculation suggests would be needed, based solely on the inputs you entered. It is an illustration, not a quotation, and it should be read alongside the other outputs rather than on its own. A monthly figure that looks manageable in isolation can still sit within a plan whose total cost over the full term is substantial, and a calculator is helpful because it shows both views together.
Most calculators also show a total interest illustration and, in some cases, a view of the balance over time. The total interest illustration adds up the interest element across the whole term, giving a sense of the overall cost of borrowing under the stated assumptions. The balance over time shows how the outstanding amount falls gradually as repayments are made, usually slowly at first, when a larger share of each payment goes towards interest, and then more quickly as the balance reduces. Seeing that pattern can make the long-term nature of a mortgage much clearer than a single monthly figure ever could.
The Formula in Symbols
Behind most repayment calculators sits a standard formula. In symbols, it is written as M = P x r x (1+r)^n / ((1+r)^n – 1). In words, M is the monthly payment, P is the amount borrowed, r is the monthly interest rate, and n is the total number of monthly payments. The formula works by finding the regular payment that, when made every month, covers the interest charged and clears the balance by the final payment. You do not need to use the formula by hand to use a calculator well, but knowing what each symbol stands for helps you understand why changing one input changes the result. For a fuller walkthrough of the same idea, see this guide to how the repayment formula works and what each part of it means.
The formula also explains why the relationship between inputs and outputs is not always straightforward. A change in the term changes n, the number of payments, which affects both the monthly amount and the total interest. A change in the rate changes r, which affects how much of each payment is absorbed by interest before any of it reduces the balance. Because the formula compounds the rate over many payments, even a modest difference in the rate or the term can lead to a noticeable difference in the illustration. That sensitivity is exactly what makes testing different scenarios worthwhile, provided you remember that each scenario is still only an illustration based on fixed assumptions.
How to Use One Honestly
The most honest way to use a mortgage payment calculator is to test a range of scenarios rather than relying on a single result. Try a shorter term and a longer term, a lower rate and a higher rate, and a larger deposit and a smaller deposit, changing one input at a time so you can see what each change does. This approach turns the calculator from a simple answer machine into a learning tool. It shows you which inputs have the greatest effect on the monthly payment and which have the greatest effect on the total interest, and it helps you avoid being surprised later by a change you had not considered.
It is also worth thinking in general terms about what a small rate change can do. Because interest is charged on the outstanding balance month after month, a small change in the rate is not confined to a single payment. It applies across the whole term, and it changes the split between interest and balance reduction in every payment. Over a long term, those monthly differences can add up to a substantial difference in the total illustration, even when the monthly change itself looks modest. That is why a calculator result based on one rate alone should never be treated as the full picture, and why it is sensible to look at how the illustration moves when the rate moves. Used in this way, calculators can be helpful planning tools, alongside other calculators as planning tools that help you explore long-term figures before making any decision.
What a Calculator Does Not Show
A mortgage payment calculator leaves out a great deal, and understanding those omissions is just as important as understanding its outputs. It does not normally include fees, charges, insurance costs, or taxes, all of which can affect the real cost of buying and owning a home. It does not show how a rate might change over time, how your income or spending might change, or whether a particular plan would be affordable for you in practice. It also cannot judge personal eligibility, because eligibility depends on detailed checks and criteria that a simple calculator does not perform and cannot replicate.
- Fees and charges connected with arranging or administering a mortgage.
- Insurance, maintenance, and other costs of owning a home.
- Taxes and other charges that may apply in your situation.
- Future changes in interest rates, income, or personal circumstances.
- Affordability decisions and personal eligibility, which require proper assessment.
Another common misunderstanding is to treat the calculator result as a budget on its own. A monthly payment figure tells you nothing about the rest of your spending, your savings, your plans for the future, or how comfortable you would be if circumstances changed. A responsible use of the tool is to place its illustration alongside a broader view of your finances, and to recognise where the calculator stops and where wider judgement begins. If the illustration raises questions about affordability, risk, or long-term planning, those questions are best explored with proper guidance rather than answered by running the calculator again with different figures until the result looks more comfortable.
A Sensible Way to Read the Result
In short, a mortgage payment calculator is best read as a clear, consistent illustration, not as a recommendation or a forecast. It explains how loan amount, deposit, term, rate type, and repayment structure combine to produce a monthly payment, a total interest illustration, and a balance over time. It lets you test scenarios honestly, compare trade-offs between term and total cost, and develop a feel for how sensitive the result is to small changes. What it cannot do is account for fees, insurance, taxes, rate changes, affordability, or eligibility, and it should never be used as a substitute for those wider considerations.
Disclaimer: This article is general information only and is not personal financial advice. It explains how mortgage payment calculators work in general terms and does not recommend borrowing any amount or choosing any particular mortgage. If you are worried about debt, struggling with payments, or unsure about your options, free and independent help is available from organisations such as StepChange, National Debtline and Citizens Advice, who can discuss your situation and explain the support that may be available.

Post Comment